Building Through the Boom: How Atlanta Contractors Can Protect Their Margins
GBC | Customer Education
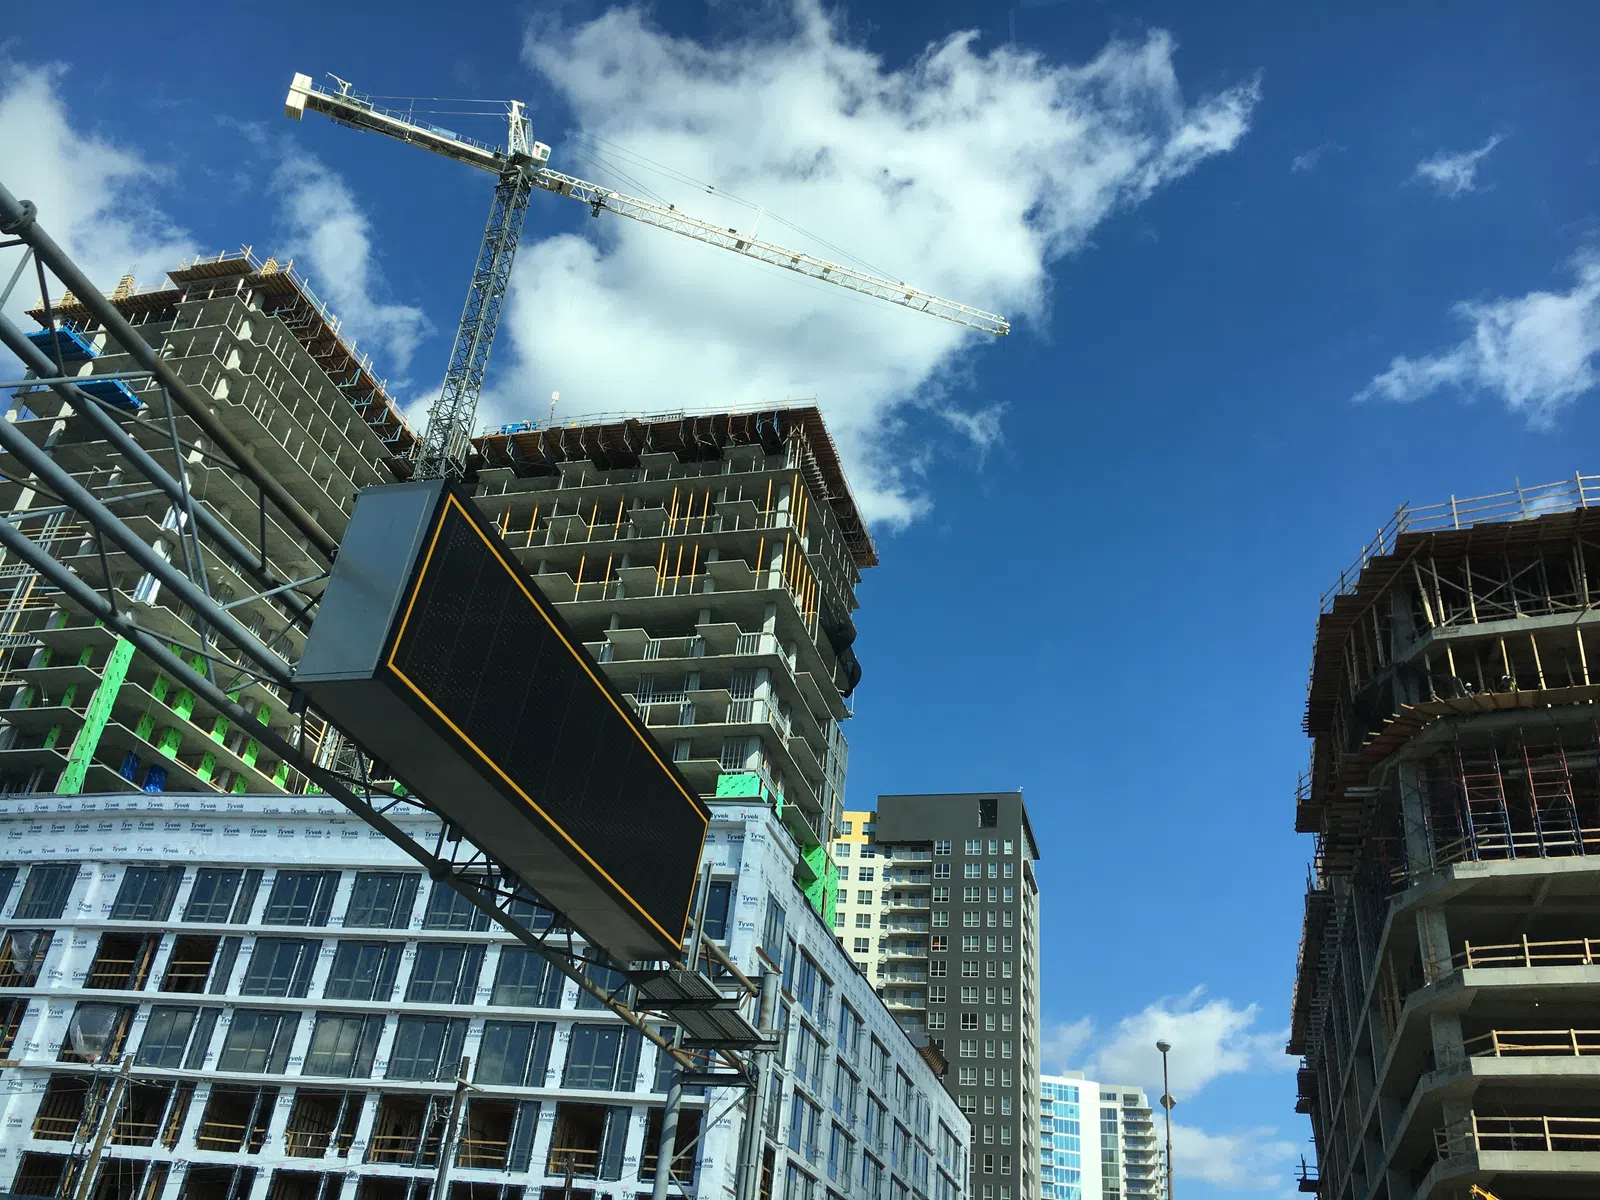
It's a good time to be busy in Atlanta construction—but it can be a hard time to stay profitable.
The Atlanta area and surrounding region are in the middle of
a building cycle with few noteworthy developments. Metro Atlanta now has
roughly 2,882 megawatts[SG1]
of data center capacity under construction, the largest pipeline of any
primary market in the country. Add the industrial, multifamily, and
infrastructure work moving alongside it, and there is more happening here than
most construction crews can staff.
However, a full schedule does not automatically become a
good year. For a lot of small and mid-sized contractors, this boom has arrived
with a cost structure that moves faster than their bids do.
The Squeeze Behind the Boom
Three pressures are landing at the same time for Atlanta
contractors.
1. Material costs move faster than your bid. Construction material prices started climbing again in early 2026 after a few quieter years. Not to mention that steel, aluminum, and copper can swing in a matter of weeks. On a fixed-price job, whatever you didn't see coming comes out of your margin.
2. Labor is tight, and the boom is making it tighter. Georgia's construction sector needs roughly 10,000 more workers each year just to keep pace with the Atlanta construction boom. The big data center projects are paying premium rates for electricians, steelworkers, and concrete crews — so smaller jobs are bidding against them for the same people.
3.
You are financing the work before you are
paid for it. Payroll runs weekly, and materials are due on delivery.
Progress billing, retainage, and 60- to 90-day payment cycles mean you are
often carrying a month or more of project costs on your own balance sheet.
"When I talk with the contractors I work with, one
of the biggest challenges they share is having plenty of work but not enough
cash available at the right time. A strong pipeline only pays off if you have
the working capital to protect your margins along the way."
— Mumtaz Prodhan, Retail Market Leader, Georgia Banking Company
4 Financing Moves That Protect Your Bottom Line
1. Put a working capital line in place before you need
it.
The best time to set up a line of credit is when your
financials look strong, not when a project has already stretched you thin. An
unused line of credit costs you nothing and gives you room to cover payroll and
material buys while you wait on a draw or a retainage release. See how it works
in our business
line of credit blog.
"I've worked with contractors who waited until a
delayed payment or unexpected material purchase created a cash crunch before
discussing financing. My advice is to put a line in place while the business is
strong, so the capital is ready when the opportunity—or the
unexpected—arrives."
— Chris Garber, Retail Market Leader, Georgia Banking Company
2. Match the instrument to the timeline.
A short-term cash gap and a long-term asset are different problems that call for different structures. Using a revolving line to fund equipment you will own for a decade gets expensive. Remember, construction loans, C&I lending, and commercial real estate financing exist as separate products because the timelines can be seriously different.
3. Get faster at collecting.
Financing is only half the equation. Treasury tools that speed up receivables (like electronic payments, remote deposits, and automated reconciliation) shorten the window you are funding out of pocket. Every day you take off your collection cycle is a day you do not need to borrow.
4. Buy ahead when the pricing is right.
When prices on a
material are climbing, buying early protects your margin. But you can only do
that if the cash is there on the day the deal shows up—which means the
financing needs to be in place before you need it.
What to Look for in a Construction Lender
Not every lender understands how construction gets paid.
Here are a few things worth asking about:
· Speed and certainty. In a market moving this fast, a maybe that takes six weeks could cost you the job.
· Local decision-making. A lender whose credit team sits in Georgia should understand what a site is worth and why a given permit timeline runs the way it does.
·
Coverage across the full project life. Financing
the construction period is one conversation. Permanent financing is another. A
partner who can structure both saves you from re-underwriting mid-project.
Big Bank Capabilities, Without Big Bank Hassle
Construction and real estate are not a side category at GBC.
Our Commercial Real Estate group works with Atlanta developers and investors
across ground-up, value-add, and stabilized projects. Our C&I team
structures growth capital, acquisition financing, and refinancing for small
business and middle market clients. And our construction lending covers both
the build period and long-term financing, with decisions made locally so you
get an answer while it still matters.
Most importantly—you get a banker who picks up the phone and
knows your name. Ready to talk it through? Book time with a Bold Banker.
Frequently Asked Questions
Should I use a line of credit or a construction loan?
A line of credit covers short-term working capital: payroll, materials, and the gap between billing and payment. A construction loan funds a specific build, with draws tied to project milestones. Plenty of contractors use both.
What does local decision-making actually change?
Speed and context. When the people approving your loan know
the market, you get answers faster and spend less time explaining a submarket
to someone who has never seen it.
How do lenders look at retainage and receivables?
A lender who understands construction will look at the quality and aging of your receivables, your customer concentration, and how retainage is structured across your contracts, not just the top-line revenue number.
Georgia Banking Company
The Bank of Choice